The GENIUS Act implementation timeline matters to anyone planning to issue, support or integrate a payment stablecoin in the United States. The Act, Public Law 119-27, was signed in July 2025. It sets a framework for permitted payment stablecoin issuers, and it takes effect no later than 18 January 2027, with agencies writing the detailed rules in between.
Regulators have been publishing proposals through 2026, covering licensing, prudential standards, state regime principles and anti-money laundering. Some pieces, such as certain Federal Reserve rules and foreign issuer criteria, were still outstanding in the commentary available at the time of writing.
This guide lays out the timeline, explains what each proposal covers and suggests a readiness plan. Rulemaking is moving quickly, so check the current status with the agencies and with counsel before you rely on any date. It is general information, not legal advice.
Why the GENIUS Act implementation timeline matters
The Act creates a federal regime for payment stablecoins. It requires issuers to hold reserves backing each outstanding token, to honor redemption, to follow prudential and compliance standards and to avoid certain activities. Only permitted payment stablecoin issuers may issue payment stablecoins in the United States once the regime applies.
The timing matters for planning. Building reserve management, redemption operations, AML programs and governance takes many months. If an issuer waits for final rules and then starts, it may not be ready by the effective date.
Key dates in the GENIUS Act implementation timeline
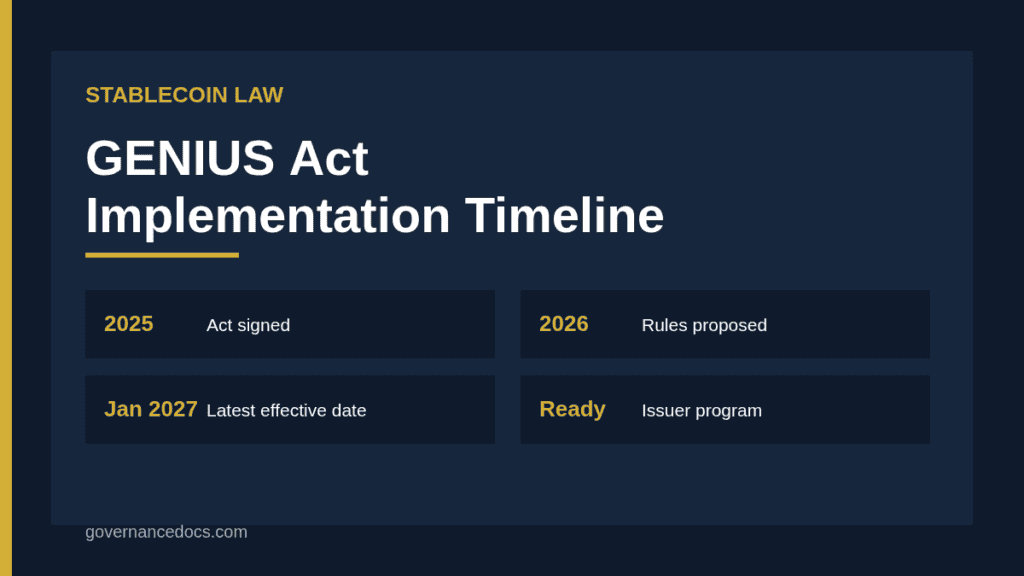
The Act was signed in July 2025. Regulators were given about a year to issue implementing regulations, with a statutory deadline of 18 July 2026. The Act takes effect on the earlier of 18 months after enactment, which is 18 January 2027, or 120 days after the primary federal regulators issue final regulations, as summarized in published commentary.
In practice, the outer date of 18 January 2027 is the one most planners use. If final rules arrive early, the effective date could come sooner, so track the agencies.
Some provisions also have later transition dates, for example for certain digital asset service providers and for foreign issuers. Check the text of the Act and current agency statements for details that apply to you.
Date
Milestone
Why it matters
July 2025
GENIUS Act signed
Sets framework and deadlines
Sept 2025
Treasury advance notice
Early input on implementation
Dec 2025 to Apr 2026
FDIC, NCUA, OCC and Treasury proposals
Licensing, prudential and state principles, AML
18 July 2026
Statutory deadline for regulations
Agencies expected to finalize rules
18 Jan 2027
Latest effective date
Act takes effect at the latest
What regulators have proposed
Law firm summaries list a sequence of actions. Treasury issued an advance notice in September 2025. The FDIC proposed licensing procedures for subsidiaries of insured banks in December 2025. The NCUA proposed a licensing framework for credit union related issuers in February 2026. The OCC proposed a comprehensive framework in March 2026, covering several issuer categories.
In April 2026, Treasury proposed principles for evaluating state regimes, and the FDIC proposed prudential standards. Treasury, FinCEN and OFAC proposed anti-money laundering and sanctions requirements. In June 2026, the FDIC published a proposed rule on Bank Secrecy Act and sanctions standards for supervised issuers, available at FDIC proposed rule on BSA and sanctions standards for stablecoin issuers.
These are proposals unless and until finalized, and final rules may differ. Watch for Federal Reserve proposals and rules on foreign issuers, which were outstanding in the commentary reviewed.
State and federal paths
The Act allows states to license issuers with no more than 10 billion dollars in outstanding stablecoins, if the state regime is substantially similar to the federal framework. Treasury has proposed principles for evaluating those state regimes. Larger issuers must operate under a federal regime.
An issuer should decide early which path fits its size and plans. The details of state qualification are covered in GENIUS Act state qualified issuers. Bank subsidiaries, federal qualified issuers and state qualified issuers follow different application routes, so the timeline varies by type.
Consult the relevant regulator early. Application processes often involve detailed questions about governance, reserves, risk management and technology.
Reserve and redemption readiness
The Act requires reserves that back outstanding payment stablecoins on a one to one basis, held in permitted assets, together with redemption at par within a specified time. The details are covered in GENIUS Act reserve requirements and GENIUS Act redemption.
Readiness tasks include designing the reserve policy and custody arrangements, defining daily reconciliation, building redemption procedures and setting service levels, and preparing public disclosures. Test the processes with realistic volumes and stress scenarios.
Treat the operating model as a whole. Redemption requests, reserve liquidity, banking partners and technology all interact, and weaknesses in one area can undermine the others.
AML, sanctions and compliance program readiness
Issuers will be expected to maintain anti-money laundering and sanctions programs, with customer identification, monitoring, reporting and technical capability to block or freeze transactions where lawful. The proposals from Treasury and the FDIC describe these expectations. See GENIUS Act AML requirements and GENIUS Act compliance requirements.
Begin with a risk assessment that covers customers, products, blockchains, counterparties and geographies, then design the program around it. Build governance around a named compliance officer and a clear reporting line to senior management.
Also consider how the regime compares to other jurisdictions if you operate internationally. See GENIUS Act vs MiCA.
A readiness plan for the GENIUS Act implementation timeline
Work backwards from 18 January 2027. In the first phase, decide your issuer category, confirm the licensing path and map the gaps against the proposals. In the second, design reserves, redemption, governance, AML and technology controls, and prepare application materials. In the third, implement and test, update policies, train staff and run a full readiness review.
Assign owners and dates. A steering group that includes legal, compliance, finance, technology and the business should meet regularly and track risks to the timeline. Budget for legal advice, technology changes and licensing fees, as discussed in GENIUS Act compliance cost.
Keep a change log for rule updates. Every time an agency publishes a proposal or final rule, review it against your plan and adjust.
A short GENIUS Act implementation timeline example
Suppose a fintech plans to issue a dollar stablecoin under a state regime. It confirms that expected circulation stays below the 10 billion dollar cap, and it selects a state with a regime that Treasury is likely to consider substantially similar. In the first quarter of the plan, it drafts the reserve policy and chooses a custodian.
In the second quarter, it builds the redemption workflow and the AML program, and submits the application. In the third, it tests redemptions under stress, completes the audit of its controls and trains staff. The fourth quarter is for final adjustments as rules are finalized. The plan is invented for illustration, but it shows how a GENIUS Act implementation timeline turns into quarterly milestones.
Real dates depend on the regulator’s processing times, so build contingency into the schedule.
Risks to watch in the GENIUS Act implementation timeline
Three risks stand out. First, rule changes: final rules may differ from proposals, so designs that depend on a specific detail may need rework. Second, dependencies: licensing decisions, banking relationships and custody providers all have their own lead times. Third, capacity: compliance, legal and technology teams will be busy across the industry at the same time, so hiring and vendor selection can slip.
Reduce these risks by keeping the design modular, starting vendor conversations early and agreeing decision points with leadership. Review the GENIUS Act implementation timeline monthly, record each assumption you are making about the rules and revisit it whenever an agency publishes something new. Keep counsel involved throughout, since interpretations can change as regulators issue guidance and answer questions from applicants.
Using a ready-made GENIUS Act toolkit
Drafting dozens of policies, procedures and forms for a new regime is slow. A prepared set of templates gives issuers and service providers a structure to adapt as rules are finalized.
The GENIUS Act Toolkit provides 126 editable templates in 18 sections that follow the Act’s own structure, including reserves, redemption, AML and governance. Because the rules are still being finalized, treat the templates as a starting point and update them as the agencies publish final text.
Use the GENIUS Act implementation timeline above to sequence the work, and review it each month.
GENIUS Act implementation timeline FAQ
When does the GENIUS Act take effect?
No later than 18 January 2027, or 120 days after final primary regulations, whichever is earlier, according to published summaries of the Act.
Are the implementing rules final?
Many were proposals in the commentary reviewed, including OCC, FDIC, NCUA and Treasury proposals. Check the agencies for final rules.
Who can issue payment stablecoins?
Permitted payment stablecoin issuers, including bank subsidiaries, federal qualified issuers and state qualified issuers within the Act’s limits.
What is the state issuer cap?
States may license issuers with no more than 10 billion dollars in outstanding payment stablecoins, under regimes substantially similar to the federal framework.
Should I wait for final rules?
Waiting can leave too little time. Many issuers begin design work now and adjust as rules are finalized.