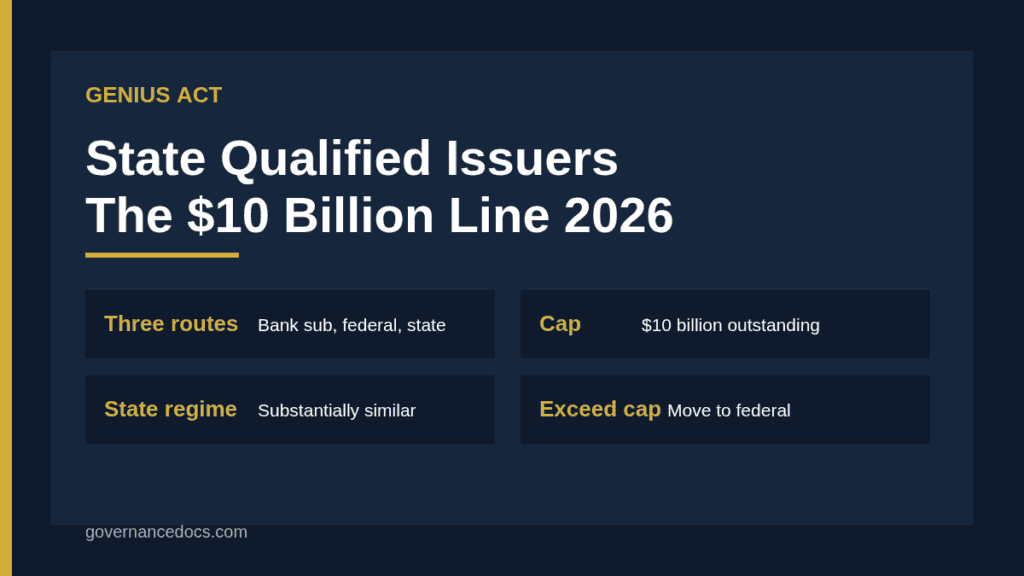
GENIUS Act state qualified issuers are stablecoin issuers that choose a state regulator, not a federal one, as their primary supervisor. The choice is attractive for smaller issuers, but it carries a size cap and depends on the state’s rules being judged equivalent to the federal framework. This guide explains how the state route works, what the $10 billion line means, and what a state-regulated issuer should prepare.
Law-firm summaries describe three categories of permitted payment stablecoin issuer.
Route
Who it suits
Primary supervisor
Subsidiary of an insured depository institution
Banks and credit unions
Federal banking regulator
Federal qualified issuer
Nonbanks, uninsured national banks, federal branches
Office of the Comptroller of the Currency
State qualified issuer
Entities formed under state law
State regulator
The state route exists so that issuers already licensed under state money transmission or trust charters can continue under familiar supervisors. It is not a lighter regime in every respect. Reserve, redemption and anti-money laundering duties come from the federal law whichever route you take.
The $10 billion line for GENIUS Act state qualified issuers
According to summaries of the statute, a state qualified issuer is limited to $10 billion of outstanding stablecoins. Once an issuer passes that level, it must do one of three things: move to federal regulation within 360 days, obtain a waiver from federal regulators, or stop issuing new stablecoins until its outstanding amount falls back below the threshold. Treat this as a planning constraint and monitor the balance continuously, not once a quarter.
If you expect fast growth, plan the federal transition early. Moving to a new regulator takes time, so start preparing well before you reach the cap. Prepare an application file, map your policies to federal expectations and speak to your state regulator about the process.
What “substantially similar” means for state regimes
A state cannot simply declare its own law equivalent. Under the statute as summarised by law firms, states must certify their regimes as substantially similar to the federal framework, and the certification is renewed annually through the Treasury Secretary and reviewed by the Stablecoin Certification Review Committee. If a state’s certification lapses, issuers under that regime move to federal oversight regardless of their size.
In April 2026 Treasury proposed a rule on how this test will work, according to a law-firm summary. The proposal was described as not final, with comments due 2 June 2026. It distinguishes uniform requirements that must be identical across states from state-calibrated requirements that may differ.
Category
Examples in the proposal
Uniform (must be identical)
Reserve requirements, monthly reporting, anti-money laundering and sanctions compliance, prohibition on paying interest
Check whether the proposal has been finalised, and read the final text, because details may change. A key benefit described in the commentary is that issuers under an approved state regime could operate nationwide without additional state licensing.
What a state qualified issuer still has to do
Choosing a state regulator does not remove federal-level duties. Prepare for the following.
Monthly reporting. The uniform category in the proposal includes monthly reporting.
Anti-money laundering. Build a programme that meets federal standards. Our AML requirements guide covers the elements.
Redemption. Have clear, tested processes for redeeming stablecoins at par.
No interest. Do not pay interest or yield to holders for holding the stablecoin.
Timing depends on the effective date, which the statute ties to the earlier of a fixed period after enactment or a set number of days after final implementing rules. Our page on the GENIUS Act effective date tracks it.
Choosing between state and federal routes for GENIUS Act state qualified issuers
Expected size. If you expect to exceed $10 billion within a few years, plan for federal supervision from the start or prepare the transition.
Existing licences. An issuer already licensed in a state may find the state route faster and cheaper.
Geographic reach. A state route works nationwide only if the state’s regime is certified as substantially similar.
Regulator relationship. Consider the supervisory approach, examination cycle and fees.
Cost. Compare the cost of building compliance under each route. Our GENIUS Act compliance cost guide gives a starting point.
Foreign issuers compared
Foreign issuers face different conditions. Summaries say their jurisdictions must be found by the Treasury Secretary to have a comparable regulatory and supervisory framework, and the issuer must be able to comply with lawful US orders, including asset freezes and sanctions directives. These conditions are separate from the state route, but firms with cross-border models should read both. For an international comparison, see GENIUS Act versus MiCA.
Governance for GENIUS Act state qualified issuers
Whichever regulator supervises you, the board should own the stablecoin risk. GENIUS Act state qualified issuers should set up a small governance framework early: a named accountable executive, a compliance officer with direct access to the board, a risk committee that meets regularly and a clear escalation route for reserve or redemption problems. Document these roles in policy and record decisions in minutes. Examiners in any regime will ask who is responsible when a reserve shortfall or redemption delay arises, and the answer should not depend on one person.
Regular testing matters too. Run redemption drills, reserve reconciliations and sanctions-screening tests, and record results with dates and owners. Independent review, whether internal audit or an outside firm, adds credibility. A calendar that shows the reporting deadlines, certification dates for your state regime and internal review cycles keeps the programme on track.
Tracking regulatory change
Because implementation is still under way, assign someone to track federal rulemaking, Treasury notices and your state regulator’s updates. When a rule changes, update the affected policy and log the change, so you can show that the programme kept pace. Subscribe to official notices as well as law-firm alerts, since firms summarise and sometimes disagree. When two sources conflict, go to the primary text and ask counsel.
Also keep a simple register of open questions, for example how your state’s certification will be handled or how the cap is measured. Review it monthly, and close each item with a documented decision. Regulators generally respond well to issuers that show they identified uncertainty and managed it, and less well to those that ignored it.
Finally, keep customer communication consistent with your regulatory status. Marketing should never imply federal backing or deposit insurance for the stablecoin, and disclosures should describe the reserve, the redemption process and the regulator accurately. Legal review of public statements protects you from misleading claims.
A hypothetical example
A hypothetical payments company holds a state trust charter and plans to issue a dollar stablecoin. It expects around $2 billion outstanding in year one and possibly more later. It applies as a state qualified issuer, builds its reserve and reporting processes to the uniform federal standards, and sets an internal alert at $8 billion outstanding to begin preparing a federal application. Two years later a change in its state’s certification status forces a review, and because the company had documented its controls against the federal framework, the transition is orderly. The example is invented for illustration.
Common mistakes for GENIUS Act state qualified issuers
Assuming the state route means lighter reserve or anti-money laundering duties.
Ignoring the state certification risk, which can force a move to federal oversight.
Monitoring outstanding amounts only occasionally, so the cap is crossed without a plan.
If you would rather not build policies, reserve procedures and reporting templates from scratch, the GENIUS Act Toolkit provides documents you can adapt to your chosen route. Have counsel review them for your licence type.
GENIUS Act state qualified issuers FAQ
What is the cap for a state qualified issuer?
Summaries of the statute describe a $10 billion limit on outstanding stablecoins. Above it, the issuer must move to federal regulation, obtain a waiver or stop issuing new coins.
How long is the transition to federal regulation?
Law-firm summaries say 360 days after passing the threshold. Confirm this in the statute and final rules.
Can a state set its own rules?
Only within limits. The state regime must be certified as substantially similar to the federal framework, and certification is renewed annually.
Is the state route cheaper?
Not necessarily. Reserve, reporting and anti-money laundering duties are similar, so compare total build and supervision cost.
Is the substantially similar rule final?
A law-firm summary describes it as proposed in April 2026. Check for a final rule before relying on the detail.